The Dominoes Fall
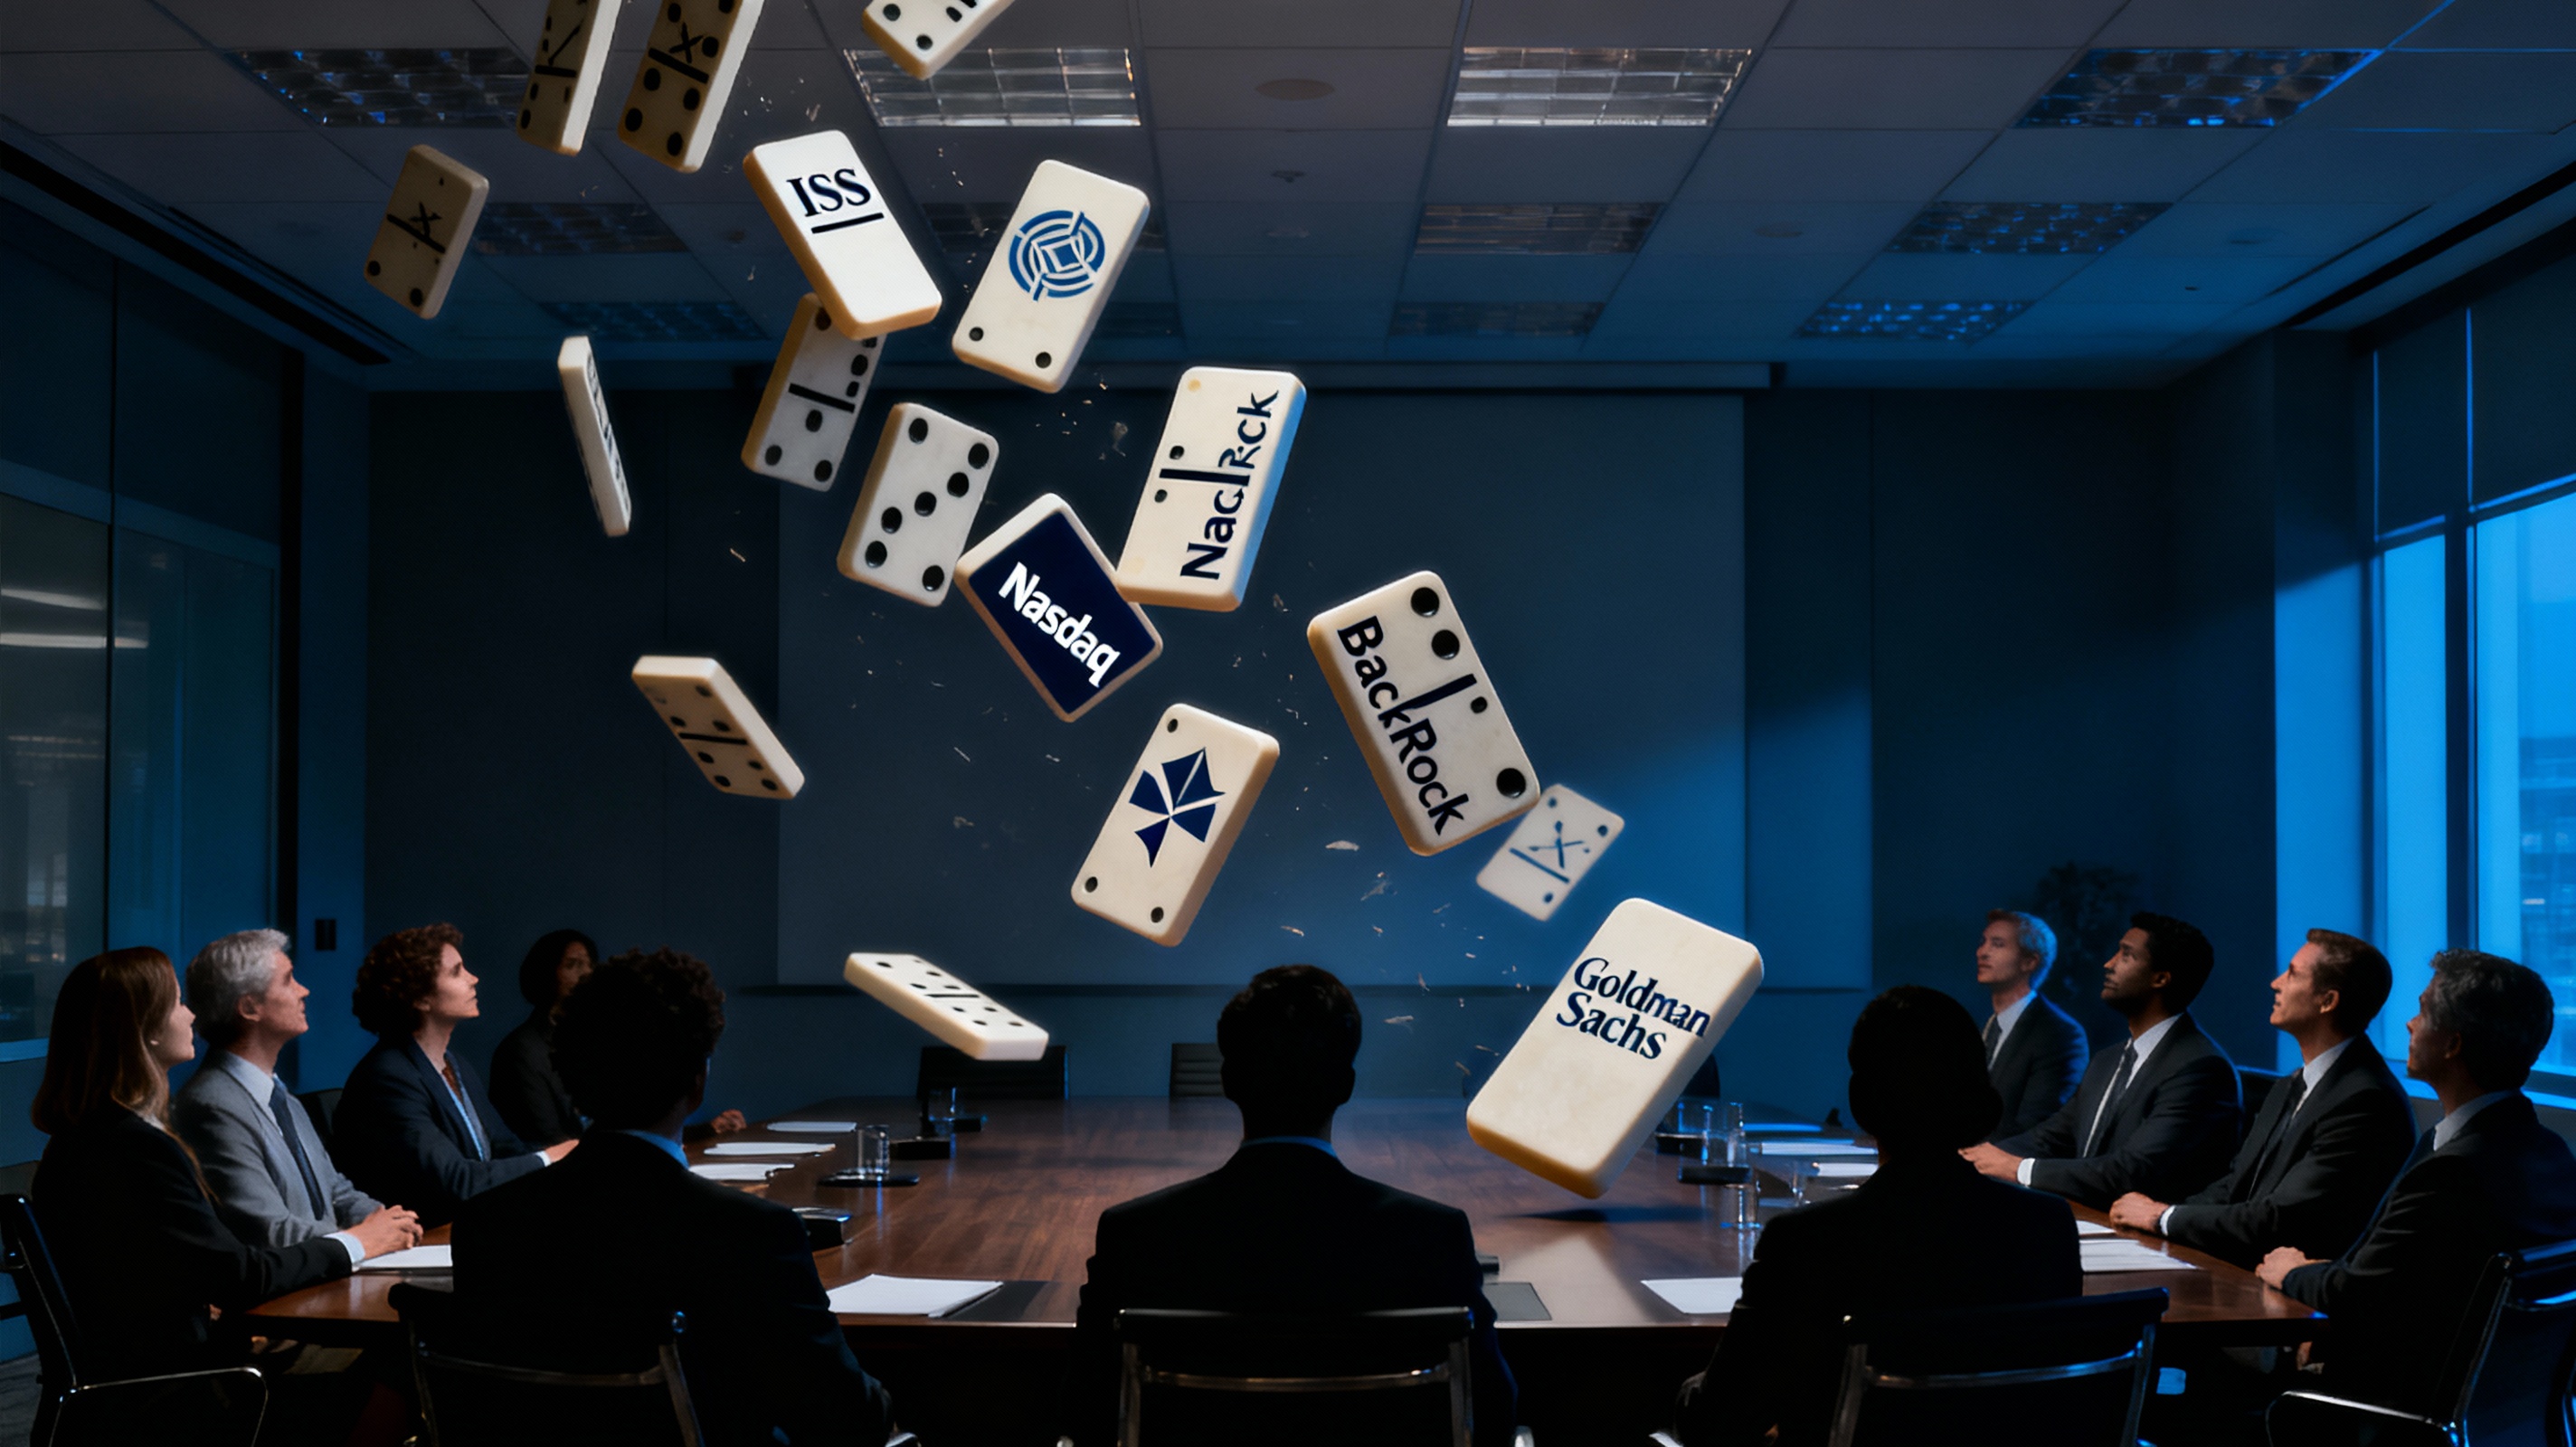
In the span of ninety days in early 2025, nearly every major institutional pillar supporting board diversity requirements in America collapsed.
February 2025: ISS (Institutional Shareholder Services), the most influential proxy advisory firm in the world, announced it would no longer consider gender or racial diversity as factors in its voting recommendations for directors.
December 2024: The Fifth Circuit Court of Appeals struck down Nasdaq's board diversity disclosure rules, ruling that the SEC exceeded its authority in approving them.
February 2025: Goldman Sachs abandoned its four-year-old policy requiring at least two diverse board members for companies it takes public.
January 2025: BlackRock, the world's largest asset manager, removed its previous numerical diversity targets—30% diverse directors, at least two women—from its voting guidelines.
What had been building momentum for over a decade—board diversity requirements backed by regulators, proxy advisors, institutional investors, and investment banks—reversed with stunning speed.
The question now: Was the diversity push a temporary aberration returning to norm, or a genuine advancement being rolled back? And what does this mean for boards, companies, and the people who serve on them?
How We Got Here
The Build-Up (2015-2023)
Board diversity went from aspiration to expectation in less than a decade.
The regulatory push:
- California mandated female directors (2018) and directors from underrepresented communities (2020)
- Nasdaq required diversity disclosure or explanation (2021)
- SEC approved enhanced diversity disclosure requirements
- State legislatures across the country considered similar mandates
The institutional investor push:
- BlackRock, Vanguard, and State Street adopted explicit diversity expectations
- Proxy advisors (ISS, Glass Lewis) began recommending against non-diverse boards
- Pension funds added diversity to their governance criteria
- ESG ratings incorporated board diversity metrics
The market push:
- Goldman Sachs refused to take companies public without diverse boards
- Major law firms and investment banks adopted diversity requirements
- Board diversity became a standard governance expectation
By 2023, the question wasn't whether boards should be diverse—it was how quickly remaining gaps would close. Diversity advocates declared victory. Governance consultants built practices around diversity compliance.
The Backlash (2023-2025)
Then came the backlash—legal, political, and institutional.
Legal challenges:
- Alliance for Fair Board Recruitment sued Nasdaq, arguing its rules exceeded exchange authority
- Lawsuits challenged California's board diversity mandates as unconstitutional quotas
- Courts increasingly sided with challengers, finding diversity requirements legally vulnerable
Political shift:
- The Supreme Court's 2023 affirmative action ruling in Students for Fair Admissions created new legal landscape
- Political pressure mounted against "DEI" programs broadly
- State attorneys general threatened action against diversity requirements
- Corporate diversity programs faced increasing legal scrutiny
Institutional retreat:
- Asset managers faced political pressure from Republican-led states
- Proxy advisors reconsidered litigation exposure
- Companies quietly deemphasized diversity communications
- The ESG backlash swept board diversity along with it
The momentum that seemed unstoppable in 2023 reversed completely by 2025.
What Actually Changed
ISS: The Bellwether
ISS's policy change matters most because ISS matters most. The firm advises institutional investors managing over $40 trillion in assets. When ISS recommends for or against a director, votes move.
What ISS changed:
- Previously: ISS would recommend against nominating committee chairs at companies without gender-diverse boards
- Now: ISS will not consider board diversity in its voting recommendations
Why ISS changed:
- Legal risk: Following the Supreme Court's affirmative action ruling, race-conscious policies face heightened scrutiny
- Client pressure: Asset managers facing political backlash sought cover
- Global inconsistency: ISS found it difficult to maintain US-specific policies different from global standards
What ISS kept:
- Disclosure expectations remain—ISS still expects companies to disclose board composition
- Individual director evaluations unchanged—qualifications still matter
- The change affects policy, not individual assessment
Nasdaq: The Legal Precedent
Nasdaq's rule required listed companies to have at least two diverse directors or explain why they don't. The Fifth Circuit found this exceeded the SEC's authority to approve exchange rules.
The legal reasoning:
- The SEC can approve rules related to exchange operations, not social policy
- Diversity requirements weren't sufficiently connected to investor protection
- The "comply or explain" structure didn't save the rule from overreach concerns
The practical impact:
- Nasdaq companies no longer face delisting threat for non-diverse boards
- The disclosure requirement—not the diversity expectation—was the rule's mechanism
- Other exchanges' potential diversity rules are now legally vulnerable
What remains:
- Nasdaq hasn't abandoned diversity advocacy—it's lost the enforcement mechanism
- Voluntary disclosure continues
- Market expectations haven't legally changed, just regulatory requirements
Goldman Sachs: The Market Signal
Goldman's 2020 announcement that it wouldn't take companies public without diverse boards was landmark. Its 2025 reversal is equally significant.
What Goldman changed:
- Previously: Required at least two diverse board members (one woman plus one person of color) for IPO clients
- Now: "Encourages" diversity without requirements
Why Goldman changed:
- Legal exposure: The policy potentially violated anti-discrimination laws post-Supreme Court ruling
- Competitive pressure: Other banks didn't maintain similar requirements
- Market reality: Enforcement was already inconsistent
What it signals:
- Market-based diversity pressure has weakened
- Soft encouragement replaces hard requirements
- IPO-ready companies face less diversity pressure than before
BlackRock: The Investor Shift
BlackRock's evolution reflects broader institutional investor retreat.
What BlackRock changed:
- Previous: Voted against directors at companies without 30% diverse boards or two women
- Now: Evaluates diversity as one factor among many, without numerical thresholds
The stated rationale:
- "One-size-fits-all" policies don't serve diverse markets and company situations
- Numerical targets may not reflect governance quality
- Regional differences require flexible approaches
The political context:
- Republican state treasurers threatened to pull funds from BlackRock
- Texas, Florida, and other states attacked ESG investing broadly
- BlackRock faced congressional scrutiny over its voting policies
What Hasn't Changed
Despite the reversals, important elements remain:
Disclosure Expectations
Companies still face disclosure requirements:
- SEC rules require board diversity disclosure
- Proxy statements must describe diversity policies
- Investors still ask about board composition
- Ratings agencies still track diversity metrics
Disclosure creates accountability even without voting consequences.
Market Preferences
Many institutional investors still prefer diverse boards:
- European investors maintain strict diversity expectations
- Some US institutions retain diversity policies despite ISS changes
- Diverse boards correlate with broader investor appeal
- LP pressure on asset managers continues in some segments
The market signal is mixed, not reversed.
Talent Preferences
Director and executive talent increasingly expects diversity:
- Candidates assess board composition before accepting roles
- Non-diverse boards face recruiting disadvantages
- Younger executives particularly value inclusive environments
- Reputation effects persist regardless of requirements
Market pressure from the talent side hasn't reversed.
Business Case Arguments
The business case for diversity—to the extent it existed—hasn't changed:
- Diverse perspectives still contribute to decision quality
- Diverse boards still better represent diverse customers
- Risk identification still benefits from varied viewpoints
- The arguments are neither stronger nor weaker than before
What changed is mandatory enforcement, not underlying logic.
The Practical Impact
For Companies
Immediate:
- Compliance pressure reduced—no ISS votes against non-diverse boards
- Disclosure requirements unchanged—still must report composition
- Legal risk of diversity programs increased—race-conscious efforts face scrutiny
Strategic:
- Diversity becomes choice, not requirement
- Companies can pursue diversity without institutional pressure or can deprioritize
- Market differentiation possible—diverse boards can signal values to stakeholders who care
- Regional considerations matter more—European operations may require different approach
For Board Candidates
For diverse candidates:
- Reduced "compliance demand" that drove some board searches
- Merit-based selection remains—qualifications still matter
- Some companies will accelerate diversity efforts despite reversals
- Pipeline advantages built over decade don't disappear
For all candidates:
- Board composition decisions return to companies
- Nominating committees have more discretion
- Value proposition shifts from compliance to contribution
For Investors
Institutional investors:
- Must decide whether to maintain diversity preferences despite ISS change
- Political pressure creates asymmetric risk—pro-diversity policies face more scrutiny
- European vs. US positioning differs significantly
- Passive index investors have less flexibility than active managers
Individual investors:
- Less visibility into diversity policies without ISS focus
- ESG-focused funds may maintain diversity emphasis
- Mainstream funds likely to reduce diversity weighting
What Comes Next
Scenario 1: Stabilization at Lower Level
The most likely near-term scenario: diversity progress continues but at slower pace.
Characteristics:
- Companies that value diversity maintain it
- Companies that don't, quietly stop prioritizing
- Overall diversity metrics plateau rather than reverse
- Market becomes more segmented by company values
Why likely:
- Talent preferences still favor diversity
- Some investors maintain expectations
- Reputational considerations persist
- Pipeline already developed doesn't disappear
Scenario 2: Significant Reversal
A more pessimistic scenario: board diversity meaningfully declines.
Characteristics:
- New director appointments skew less diverse
- Existing diverse directors retire without replacement
- Diversity metrics decline to pre-2015 levels over time
- Market stops valuing diversity signals
Why possible:
- Without enforcement, default behaviors return
- Companies prioritize other criteria
- Diverse candidates pursue other opportunities
- Self-reinforcing cycle of reduced diversity
Scenario 3: Bifurcated Market
An increasingly likely scenario: the market splits.
Characteristics:
- Diversity-committed companies increase efforts
- Diversity-indifferent companies reduce efforts
- Clear market segmentation by values
- Talent and capital sort accordingly
Why emerging:
- Political polarization extends to corporate governance
- Regional differences (US vs. Europe) become starker
- ESG/non-ESG investment categories harden
- Company identity becomes differentiator
The Uncomfortable Questions
The reversal forces uncomfortable questions that advocates and critics alike avoided:
Was the push ever about outcomes?
If diversity was primarily about compliance rather than conviction, the reversal reveals that. Companies that added diverse directors to meet requirements may not retain commitment without requirements.
Did mandates help or hurt?
Critics argued mandates created stigma—diverse directors seen as "compliance hires" rather than qualified contributors. Supporters argued mandates were necessary to overcome inertia. The reversal may reveal which view was correct.
What is the actual business case?
The business case for diversity was often asserted rather than proven. Without mandates, companies will make their own assessments. Market outcomes may reveal whether diverse boards actually perform better.
Who bears the cost?
The cost of reduced diversity pressure falls primarily on diverse candidates who benefited from increased demand. The cost of mandates fell on companies required to comply. The reversal redistributes these costs.
The Bottom Line
The great reversal of 2025 marks the end of an era—the period when board diversity moved from aspiration to expectation to requirement. The requirement phase lasted less than a decade and is now over.
What remains is choice. Companies can pursue diverse boards because they believe in the value. They can deprioritize diversity because requirements no longer force it. The market will sort outcomes.
For board candidates, diverse and otherwise, the criteria for selection return to pre-mandate norms—networks, experience, and fit matter more than compliance categories.
For governance advisors and executive search firms, the era of diversity-driven board searches has ended. Client preferences will drive composition, not ISS guidelines or Nasdaq rules.
The next chapter isn't predetermined. It will be written by thousands of individual board decisions, each now unconstrained by institutional requirements that no longer exist.
What companies actually value—rather than what they were required to demonstrate—will become clear.
That clarity may be the reversal's most significant consequence.